By Friday afternoon, the campaign is selling well and spending faster than planned. There is still money in the account, so another increase looks affordable. What is less obvious is that some of that money was meant to keep the offer visible on Sunday and Cyber Monday.
A BFCM pacing problem can develop while performance looks healthy. The team keeps funding the demand in front of it without recalculating what remains for the rest of the promotion. By the time it notices, the choice has narrowed to ending early, reducing later activity sharply, or asking for more money.
A useful pacing plan makes that trade-off visible while there is still time to choose. It connects the spending curve to order economics and tells the buyer when to hold, expand, reduce, or repair delivery. For BFCM 2026, the five-day Thanksgiving-to-Cyber-Monday period runs November 26–30, with Black Friday on November 27.
This playbook focuses on managing the live allowance through those five days. If you still need to establish your overall acquisition targets, start with the BFCM paid media planning guide. For the opening platform allocation, use the cross-channel budgeting guide. Here, the question is how to keep that plan workable as actual delivery changes.
Key takeaways
- Measure pacing against expected demand, using cumulative spend and an intraday curve rather than elapsed time alone.
- Check spending pace and acquisition economics separately. A campaign can be profitable but consuming later allowances, or on budget while producing unaffordable orders.
- Protect future capacity explicitly and release reserve through a recorded decision. Money already spent cannot remain available in another day's plan.
- Diagnose CPM spikes through CTR, purchase conversion, and order contribution before changing budgets.
- Separate alerts from automatic actions, allowing for reporting delays, platform delivery behavior, and the time campaigns need after an edit.
Give the budget three distinct meanings
Before the sale, agree on three numbers: the maximum commercial allowance, the amount currently authorized, and the amount the platforms could deliver under their active settings. These numbers need to reconcile, but they are not interchangeable.
The maximum allowance is what the business has approved for the event. Authorized spending is the portion released into the current plan. Platform exposure depends on budget type, delivery behavior, schedules, active rules, and edits. A nominal daily setting may not enforce the exact amount written in your pacing sheet.
Record the event's start and end in the relevant account time zones, identify who can approve a change, and specify which costs the allowance includes. If production fees or earlier acquisition activity sit outside the five-day media allowance, keep them visible in the broader promotion economics without subtracting them twice from the live budget.
Complete the pre-BFCM ad account audit before relying on live acquisition signals. A duplicate purchase event can make an overspending campaign appear efficient enough to expand.
Build a five-day curve that preserves choices
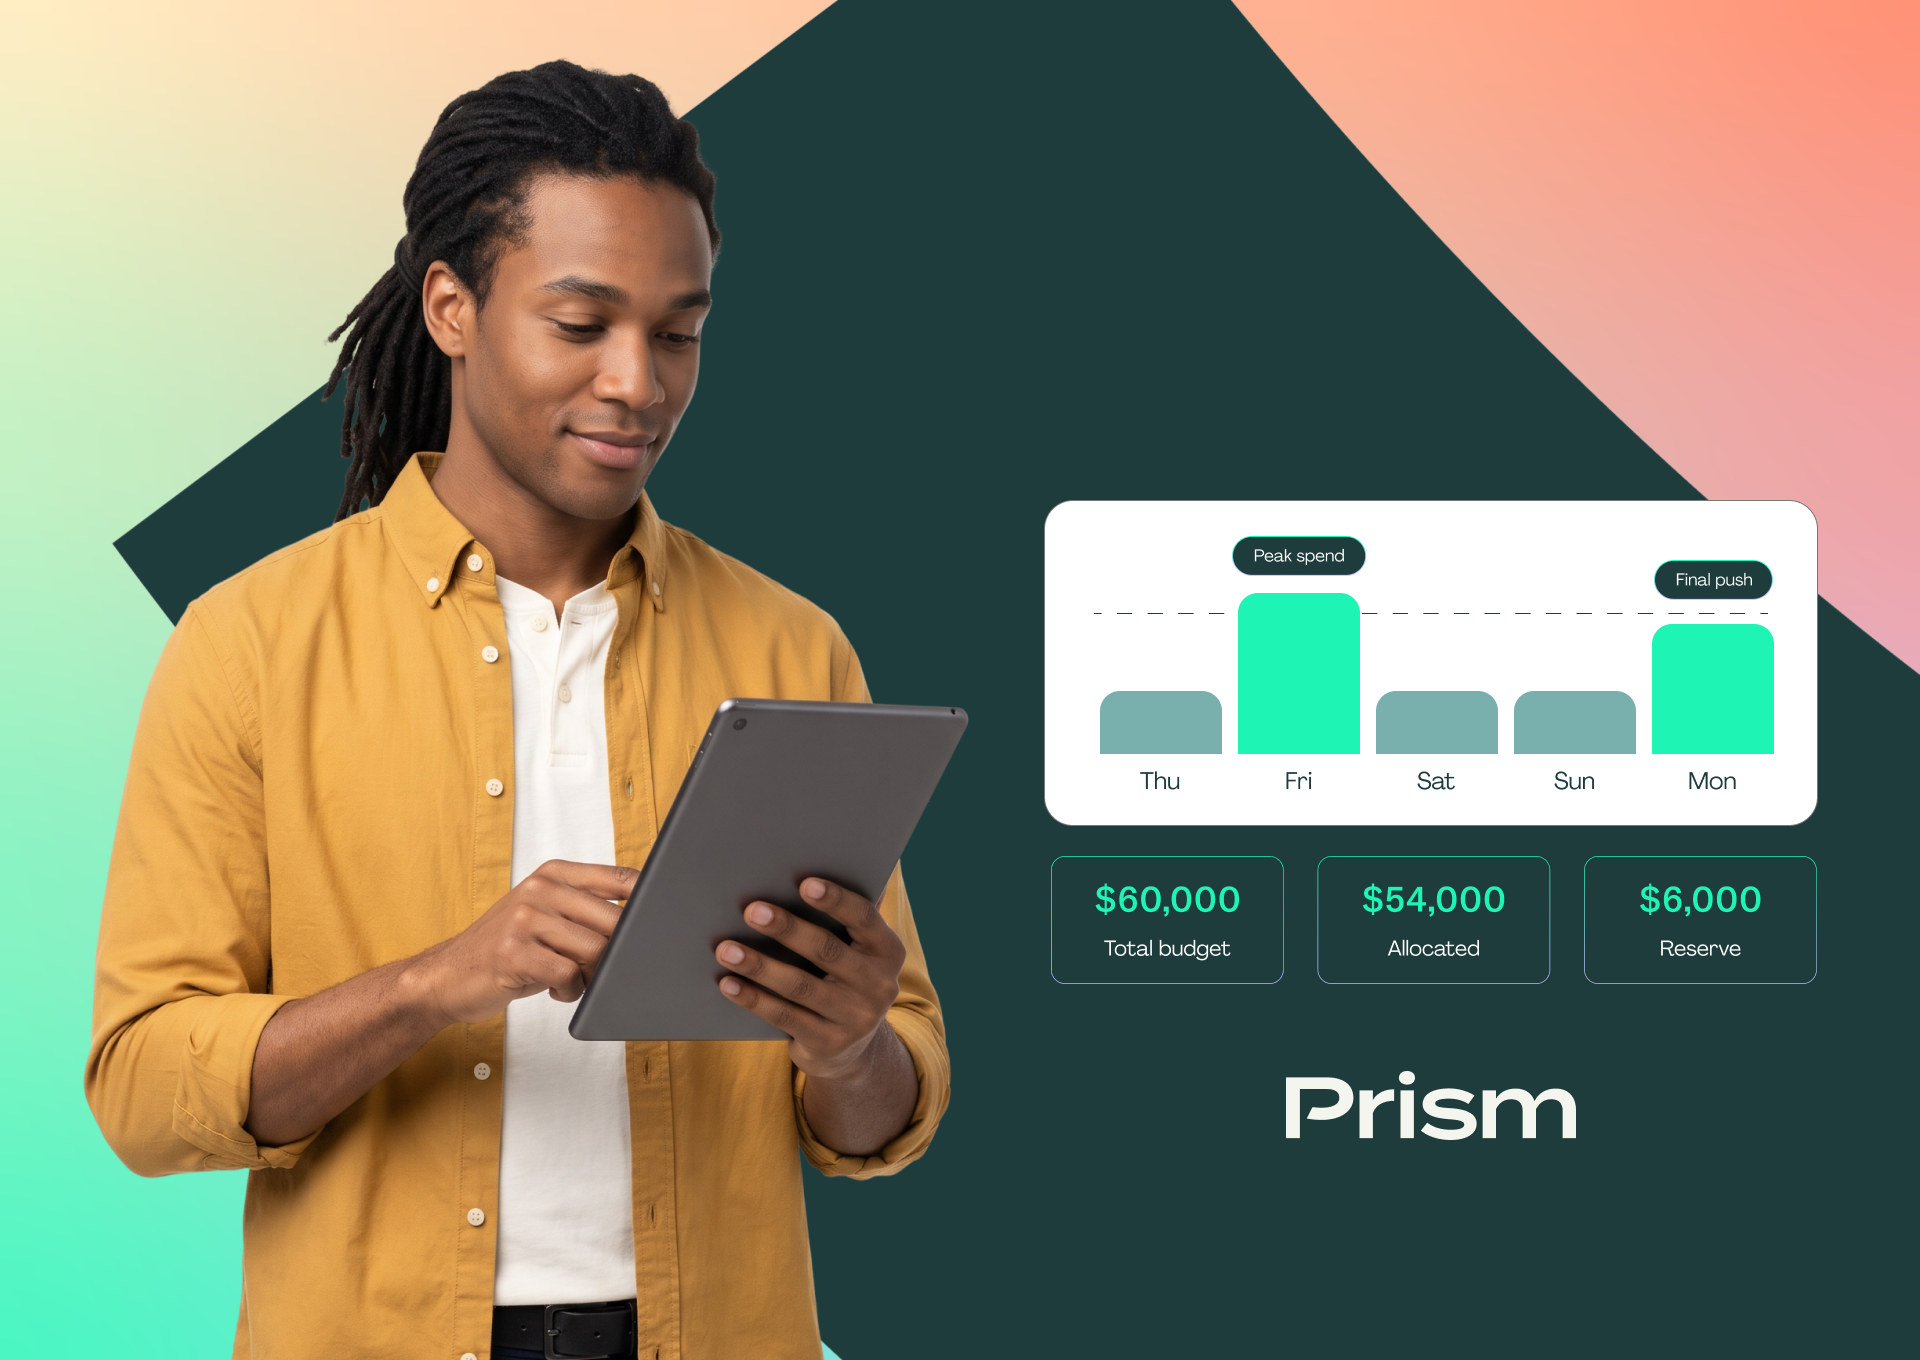
Consider a hypothetical retailer with a $60,000 maximum five-day media allowance. It authorizes $54,000 initially and holds $6,000 in reserve. Its opening daily plan is:
- Thanksgiving, November 26: $8,000. Launch the public offer and capture the demand expected around the announcement.
- Black Friday, November 27: $18,000. Fund the strongest forecast demand day for this particular retailer.
- Saturday, November 28: $7,000. Maintain viable delivery while Friday's purchase data becomes more complete.
- Sunday, November 29: $7,000. Continue the offer and retain capacity for the final day.
- Cyber Monday, November 30: $14,000. Support the final planned demand window.
Those amounts total $54,000. The $6,000 reserve is unassigned until released. This is an example of how to construct a plan, not a recommended percentage split for other brands.
Use last year's comparable offer timing, recent trading patterns, and this year's email and promotion calendar to set your curve. An early-access event may bring demand forward; a new Cyber Monday offer may justify more late capacity. Account for stock and fulfillment limits so the plan does not depend on selling unavailable products.
Track cumulative spending as well as each day
The opening cumulative allowances are $8,000 by Thursday's close, $26,000 by Friday's close, $33,000 by Saturday, $40,000 by Sunday, and $54,000 by Monday, before approved changes.
Cumulative checks reveal errors that a daily view can conceal. If Friday closes at $29,000 of event spend, the business has used $3,000 more than the original cumulative allowance. That amount must come from reserve, a future allocation, or a separately approved increase in the maximum. Leaving all three unchanged would authorize the same money twice.
Use a single pacing record with the original allocation, approved revisions, actual spend, remaining authorization, reserve balance, and projected close. Retain the original plan as a reference rather than overwriting it every time delivery moves.
Define what it takes to borrow from a later day
For the example retailer, the team protects the $14,000 Cyber Monday allocation unless a named commercial owner approves moving part of it. This is a planning rule chosen for the account, not a claim that Monday will always outperform Friday.
If strong Friday results justify bringing money forward, the decision should state how much comes from Monday, what capacity remains, and why the expected benefit outweighs the lost flexibility. Reserve can fund an opportunity without that trade-off, but once used, it is no longer available for the next request.
Measure the day against demand, not the clock
A campaign that has spent half its allowance at noon is not necessarily pacing correctly. If the retailer normally receives most paid demand after its evening email, that spending could be early. If its offer launches at dawn and demand is concentrated in the morning, the same result could be reasonable.
Create intraday checkpoints from comparable history, adjusted for the current offer. For the example's $18,000 Friday allowance, suppose the team expects cumulative spend to reach 25% by noon, 60% by 6 p.m., and 100% by close. Its checkpoints are therefore $4,500, $10,800, and $18,000.
These checkpoints describe an expected curve. They are not platform controls and should not force spending into weak hours simply to make a line look correct.
Use three pacing calculations
Pacing ratio = actual cumulative spend ÷ planned cumulative spend at the checkpoint.
If Friday spend is $6,000 at noon against $4,500 planned, the ratio is 1.33, approximately 33% ahead. A forecast based on the example curve is:
Projected day-end spend = actual spend so far ÷ expected share delivered by this checkpoint.
At $6,000 spent and a planned noon share of 25%, the implied close is $24,000. That is a warning that the $18,000 allowance may be exceeded, not a reliable prediction that demand will continue unchanged.
Then calculate the amount still authorized:
Remaining daily allowance = approved daily allowance − actual daily spend.
Here, $12,000 remains. Dividing that by the 12 hours left gives an average of $1,000 per hour, but this figure is only an exposure check. Shape the remaining delivery around the expected demand windows rather than enforcing a flat hourly rate.
When history is limited, review several plausible curves instead of pretending that a precise hourly forecast exists. Keep the initial commitment within an acceptable downside and increase monitoring where uncertainty creates material spending exposure.
Set guardrails for pace and economics separately
A spending alert asks whether delivery is consuming authorization too quickly. An efficiency alert asks whether the orders justify the spending. Combining them into one rule can produce the wrong response: pausing profitable delivery merely because it is early, or ignoring poor economics because the account is under budget.
A pacing alert should create time to act
For the hypothetical account, the team might investigate a checkpoint more than 10% above its curve when the absolute variance also exceeds $500. It might require approval when the projected close exceeds the daily allowance by more than $1,500.
These thresholds are illustrations. Set yours according to spend velocity, normal variation, reporting freshness, and the time required to intervene. A threshold that is harmless for a large account could allow a smaller account to exhaust its allowance before anyone responds.
Check the age of the spending data before acting. An automation or manual review needs enough buffer for reporting lag, the next execution, and the effect of the edit. Reaching an alert threshold is a reason to investigate; it should not automatically authorize a larger budget.
An efficiency rule needs the sale's actual economics
Suppose the retailer expects $90 in net revenue per order, $50 in variable costs before advertising, and requires $10 in contribution after advertising. It can afford $30 CPA, equivalent to 3x ROAS on that same net-revenue definition.
Use the approved definition consistently and inspect product or customer mix where it materially changes the economics. The platform's displayed purchase value may need reconciliation with the net revenue used by finance.
Evaluate recent purchase results using a window that has had time to report. Google's conversion lag reporting helps identify incomplete recent results. Historical delay can inform the review window, but it does not guarantee that BFCM customers will convert at exactly the same speed.
A stop condition should identify a confirmed failure
A broken checkout, an incorrect live price, or unavailable inventory behind an active offer can justify pausing affected delivery immediately. Waiting for more purchase data will not repair those problems.
By contrast, a short run without purchases is ambiguous. Even spending a multiple of target CPA without an order should trigger an account-appropriate review, rather than a universal automatic pause. Check normal purchase volume, conversion delay, and the buying journey before treating a small sample as decisive.
When CPM spikes, calculate what happened to order cost
A CPM increase changes the price of reaching people, but purchase economics also depend on how many respond and convert. Diagnose the movement before assigning a budget response.
At a hypothetical $24 CPM and 2% link CTR, 1,000 impressions generate 20 clicks for $24, or $1.20 per click. At a 5% click-to-purchase conversion rate, CPA is $24.
If CPM rises 50% to $36, with CTR unchanged, CPC becomes $1.80. With conversion still at 5%, CPA rises to $36, above the example's $30 limit. The team should investigate and contain spending that persistently fails the target.
But if purchase conversion rises to 6%, the same $1.80 CPC produces a $30 CPA. The campaign reaches the approved limit despite the more expensive auction. It may deserve continued delivery, although there is less room for deterioration and expansion still needs evidence.
Use consistent click and purchase definitions when calculating CPA = CPC ÷ purchase conversion rate. This relationship is most useful for comparable click-based traffic; it is not a direct reconciliation of a platform total that includes additional attribution types.
Match the response to the failure
When CPM rises while CTR and purchase conversion hold, inspect auction pressure and changes in delivery mix. Determine whether the resulting CPA remains acceptable before cutting the whole campaign.
When CPM is stable but CTR falls, investigate the creative, audience, frequency, and placements. If click costs hold while purchase conversion weakens, inspect the offer, product availability, shipping, and checkout. A budget edit may reduce exposure, but it does not fix the reason buyers stopped completing orders.
For an eligible campaign, use an already approved creative replacement where the evidence warrants it. Avoid simultaneous changes to targeting, creative, bidding, and budget unless an operational failure requires them, since several edits make the next result difficult to interpret.
Resolve an overspending Friday without losing the weekend
At noon, the example retailer is pacing toward a possible $24,000 Friday close against an $18,000 allowance. The team first checks tracking, purchase economics, inventory, and the distribution of spend across campaigns.
If orders remain affordable
The retailer can hold the original authorization and adjust delivery toward the remaining $12,000 allowance, or approve additional spending with a defined source. Suppose it releases $2,000 from reserve, making Friday's allowance $20,000.
The revised event authorization becomes $56,000 and reserve falls to $4,000. Friday's remaining allowance becomes $14,000 after the $6,000 already spent. The cumulative Friday ceiling rises from $26,000 to $28,000, while later daily allocations remain intact.
Record that decision once in the pacing plan, then implement account-appropriate changes and verify actual delivery. The authorization is permission to spend under the commercial rules, not evidence that every additional order will remain affordable.
If recent mature results breach the target
Do not release reserve merely because delivery is fast. Identify the affected campaign or product group, reduce its exposure where warranted, and investigate the cause. Keep viable activity running when the issue can be isolated.
A revised forecast should reflect the action actually taken. If a rule and another connected tool can both increase the same campaign, correct that conflict before assuming the reduction will hold.
If the account is behind plan
First establish whether the apparent underspend reflects delayed reporting, a launch error, disapproved products, restrictive settings, or weaker demand. A campaign below budget can still be spending inefficiently.
When mature economics are strong, eligibility is healthy, and evidence supports additional demand, consider a controlled adjustment. If the offer is failing to convert, a larger budget can simply buy more of the same problem. Unused authorization can remain available for later days without becoming an obligation to catch up immediately.
Check what platform settings actually control
The pacing plan is a commercial authorization. The platform configuration must be checked separately because daily averages, total budgets, and spending limits behave differently.
Google: a lower setting may not remove today's exposure
For most Google campaigns using average daily budgets, the day-of-change spending limit is based on the highest average daily budget selected that day. In Google's budget-change example, increasing a budget and lowering it later does not reduce that day's limit to twice the new lower setting.
This matters when transferring authorization or responding to an alert. Verify delivered spend and remaining exposure instead of assuming a field edit immediately frees the same amount for another campaign. Campaign total budgets have different duration-based controls, so verify which budget type is active before choosing a pacing method.
Meta: inspect the active budget and spending controls
Before launch, confirm the budget type, campaign and ad set controls, schedules, active rules, and any spending-limit features available in the actual account. Check the current in-product explanation of daily delivery and how limits apply to previously accumulated spend.
A payment threshold, a campaign allowance, and an account spending limit serve different purposes. Identify which control enforces the intended scope and which could stop unrelated activity if reached. Document the process for removing temporary settings after the sale.
TikTok: allow time for campaigns to adjust
TikTok's budget guidance advises avoiding targeting, bid, or budget changes during learning and allowing at least two days between such changes for conversion campaigns. That guidance makes repeated intraday budget edits an unsuitable default.
Prepare the allocation and coverage before launch, then separate urgent action on a confirmed failure from discretionary optimization. An operational review can happen frequently without changing every campaign at every checkpoint.
Build alerts that reach a person with authority
Automate the repetitive comparisons first: actual spend versus the checkpoint, remaining allowance, missing data, and material departures from the expected curve. Each alert should identify the affected account or campaign, data timestamp, actual and planned spend, remaining authorization, and the reason it fired.
Keep automatic budget actions narrower than informational alerts. Review the condition, lookback period, scope, maximum change, and what happens if the rule runs repeatedly. A rule that raises budget by 10% on every qualifying run can compound far beyond the increase its author intended.
Design a delay before another discretionary edit, require acknowledgment where appropriate, and make missing data an investigation state rather than treating it as zero spend or zero purchases. Check for conflicts between native rules, scripts, connected tools, and manual buyers.
Assign a primary and backup owner. The response deadline should reflect the account's spending velocity and exposure; an alert is ineffective if its recipient cannot access the account or obtain approval before the allowance is consumed.
Use Prism to connect the pacing review with the diagnosis
A pacing alert identifies a variance, while the buyer still needs to understand which campaigns produced it and whether their economics support continued delivery. Pixis Prism provides conversational campaign analysis, monitoring, and optimization recommendations, including identifying inefficiencies and simulating outcomes.
Give the review a defined scope: compare actual spending with the approved checkpoints, identify the campaigns contributing to the variance, and inspect their purchase performance over appropriate reporting windows. Supply the approved plan and commercial assumptions through the inputs supported by your workflow; do not assume that an external authorization or inventory constraint is already connected.
For example, the Friday review should establish whether fast delivery is concentrated in an affordable campaign, a campaign with incomplete conversion data, or an affected product group. The resulting recommendation can then support a specific decision about the remaining allocation and the next review.
Treat the approved pacing plan as the reference for authority. Analysis can explain a variance and recommend a response, while any execution must remain within configured permissions and spending approval. Explore Prism to discuss the campaign data, monitoring, and optimization workflow your team needs during BFCM.
Protect Cyber Monday without treating Friday as a rehearsal
Later capacity should be protected deliberately, but it should not prevent a justified decision to bring investment forward. On Sunday, reconcile actual spending, outstanding exposure, remaining authorization, reserve, stock, and the planned Monday offer.
If Friday closed at $29,000 cumulative spend without a recorded increase, the team must resolve the $3,000 difference before continuing to use the original schedule. Otherwise, the shortfall appears only when the final day arrives.
Likewise, do not automatically move every unspent dollar into Monday. Confirm that the remaining opportunity, creative, delivery capacity, and order economics support it. A large late increase may not produce efficient purchases simply because the event is ending.
At the close, remove expired messaging, review temporary settings, and reconcile final spending. Revisit performance as conversions and returns mature, retaining the record of when money was brought forward, when reserve was released, and whether those decisions improved the promotion's commercial outcome.
Your live pacing review
Use the same questions at each scheduled checkpoint so another buyer can take over without reconstructing the plan:
- Is the spending data current, and can customers complete the advertised purchase?
- How does actual spend compare with the revised cumulative curve?
- What is still authorized today and across the rest of the event?
- Which recent results are mature enough to judge against the sale's economics?
- Does a proposed change use reserve, reduce a later allowance, or require new approval?
- What action was implemented, who owns it, and when will its effect be checked?
A well-run pacing review leaves the team with an explicit decision about the money still available. That preserves the ability to support strong demand when it appears, while making the cost of each change visible before the final day.